[Excerpt from The Pickett Line June 2026 Issue]
As the “brief interlude” in US spot truckload linehaul rate inflation we described in last month’s issue continues, we’ve seen post-July 4th seasonality and relatively weak overall market demand take all-in spot rates -3% (or $0.10/mi) lower while all-in contract rates reset +6% (or $0.18/mi) higher and diesel prices rise steadily week over week. So for mid-size and smaller fleets that operate primarily in the spot market, this of course creates a ‘worst of all worlds’ scenario with falling spot rates and rising diesel costs once again on a collision course to wreak havoc on operating ratios.
For many of these fleets, the rapid rise in spot rates over much of the year just barely outpaced the surge in diesel prices as a result of the war in Iran and the disruption both in maritime traffic through the Strait of Hormuz and energy infrastructure across the Middle East. Then, when it looked like there would be a diplomatic resolution to the conflict with on-again/off-again ceasefire agreements through the Spring and early Summer, fleets finally got some relief in the form of a -20% drop in diesel from April’s peak levels. But of course, the ceasefire agreements were allowed to expire, hostilities resumed, and here we are with diesel right back at April’s peak as of this week. Only at this moment in time, spot rates are drifting lower, not higher to help offset the rise, putting spot market operating profits for most motor carriers back under extreme duress.
As diesel prices continue to whipsaw from month to month, even with spot TL linehaul rates up +40% Y/Y and the inflationary leg of a new cycle still in the middle innings, we’re reminded that plenty of risks remain for operators on either side of the market – depending on timing and positioning, among other factors. And it is in this spirit that we’re borrowing the promotional tagline for the 1978 sequel to the horror classic Jaws to characterize current market conditions: ‘Just when you thought it was safe to go back in the water spot market!’ Just when it looked like a rising tide in spot and contract rates was poised to lift all boats, here comes seasonality and an unexpected war to reconcile with. Never a dull moment in freight. Though if you believe, as we do, that both of these forces are likely to be temporary, that seasonality will swing the other direction in Q4, and that energy markets will eventually stabilize and drive diesel prices back towards pre-war levels, then these are times when one must simply grit your teeth and head back in. Or if you’re in, continue to stay the course. Damn the torpedoes…and the sharks!
So with that as our setup, welcome to the June 2026 issue of The Pickett Line, which accounts for all observed market action through the August 31st, 2026 publication date. The revised read on the Q3 2026 US Spot TL Linehaul Index now sits at +40.2% Y/Y after opening the quarter last month at +46.7% Y/Y vs. a forecast of +45.0% + 5.0%. From here, we maintain that the quarter will close roughly where we are now at +40-45% Y/Y before going on to peak at +50.0-60.0% Y/Y in Q4, though we could see more volatility along the way as diesel prices whipsaw – given their impact on linehaul rates relative to the all-in rates that the market transacts on. After closing Q2 at +6.0% Y/Y vs. a forecast of +5.0%, the Q3 2026 US Contract (Cass) TL linehaul Index opened at +9.3% Y/Y vs. a forecast of +8.0%. We continue to expect Q3 to close at +8.0%-10.0% Y/Y on the way to a peak of +15.0-20.0% by mid-2027.
So with both rate indices running mostly in range with expectation over much of the year, diesel has been the surprise wild card since the US and Israel declared war on Iran on February 28th. After surging over +52% higher Y/Y in Q2, we got a -20% correction lower on the back of a temporary ceasefire to allow diplomatic efforts to seek a peaceful resolution. We then got another dramatic reversal the other way when negotiations between the US and Iran failed and the fragile peace deal collapsed. Hostilities resumed and tanker traffic through the Strait of Hormuz was once again throttled. And this is where we stand today. Though recall that this 20% correction lower in fuel costs had been the basis for the counterintuitive hypothesis we presented in the April issue – which we dubbed ‘The next shoe to drop.’
In our usage of the phrase, the next shoe to drop was to be a collapse in diesel prices to pre-war levels in the wake of an extended ceasefire and a complete reopening of the Strait of Hormuz. With the truce collapsing and traffic through the Strait grinding once again to a crawl, diesel prices went right back on the rise, thus negating the impact on all-in contract vs. spot truckload rates that we expected would drive more freight into the spot market as contract routing guides come under increasing pressure. In the current environment, we are actually getting the exact opposite. As contract linehaul rates reset higher with the market cycle and fuel surcharge programs inflate higher with rising diesel prices, all-in contract rates are back to looking more attractive than all-in spot rates, which have been mostly on the decline since the July 4th holiday.
For more color on the whipsawing we’ve seen at the gas pump so far this year, here’s the play-by-play:
1. Diesel hits a 2026 peak of $5.643/gal the week of April 6th, the week an initial 2-week ceasefire was agreed to between the US and Iran with mediation from Pakistan.
2. On June 17th, the Islamabad Memorandum was signed remotely by the US and Iranian leadership calling for a 60-day extension of the ceasefire and formal truce talks. By that point, US national diesel prices had fallen 10% to $5.059/gal. And they continued to fade another 9% to $4.578 by the week of July 6th, just shy of a 20% correction from the April peak.
3. Fast forward to July 8th, the ceasefire collapses and fighting formally resumes. Since then, diesel has reversed course and marched 23% higher, and we’re now back over $5/gal at $5.652 and have overtaken the April peak by a penny.
So, what now? Now we wait. We wait for the next shoe to drop in the form of another collapse in diesel prices when the next peace deal is reached and the Strait of Hormuz is back open for business for maritime traffic. We noted last month that “in the meantime, most market participants should enjoy the brief interlude and period of relative market tranquility that we expect to get in August. All-in spot rates are likely to hover at current levels through quarter close; produce season is winding down; we have no major holidays; and we’re not yet deep into the Atlantic hurricane season (which is expected to be a mild one anyway due to this being a Super El Nino year). That said, it’s exactly when you get comfortable and complacent that the next black swan descends. But barring that, it should be a pretty forgiving next few weeks for most. The one exception, however, will be the owner-ops and small carriers that remain mostly, if not fully, exposed to the spot market. Flattish all-in rates with diesel prices surging will create another challenging operating environment when it comes to operating profits. So we could see some acceleration in the exodus of capacity as a result – either temporarily or permanently.” And looking back over the last month, with all-in spot van rates down only 3% M/M, and market demand mostly subdued with seasonality (the exception being in the AI infrastructure build-out), that’s pretty much what we got. As is often the case in this market, two steps forward lead to one step back before the cycle trajectory is resumed.
With Q2 2026 now further in the rearview mirror and Q3 tracking to forecast, we continue to marvel at the stoic consistency of the US truckload freight market cycle. While truckers, shippers, and brokers all endured disruptive winter weather across much of the country in January, an AI panic-induced flash crash in February, then a historic spike in diesel prices starting in March, a SCOTUS and now Texas court ruling almost nobody saw coming, spot linehaul rates marched right along in line with our forecast. We closed Q4 2025 at +4.6% Y/Y vs. a forecast of +5.0% before heating up to +18.0% Y/Y in Q1 2026 vs. a forecast of +10.0% Q3 went on to close at +33.9% Y/Y vs. a forecast of +25.0%, and Q3 now sits at +40.2% Y/Y vs. a forecast of +45.0%. While it seems we can’t go a week without a new inflationary catalyst popping up for the market to point to as the explanation for the trending rate environment, our position continues to be that this is all absolutely playing out as expected with regard to past rate cycles. Because if nothing has fundamentally changed in terms of market structure or supply vs. demand dynamics, the cycle has little choice but to repeat.
Now let’s get to work parsing last month’s macro data points and market signals to show what makes us so confident in charting the path ahead, in this special ‘Just when you thought it was safe’ June 2026 edition of The Pickett Line. Now most of the way through the third quarter of this new year, we continue to see compounding signals lining up in support of the assertion that, after three full quarters of battling through the downdraft in US truckload capacity demand triggered by the Trump Trade War, the 6th observed turn of the US TL Spot Linehaul Rate Cycle has returned to its regularly scheduled program. A few months ago, we got Q1 diesel prices bending to +11.6% Y/Y before going on to surge to +52.0% Y/Y in Q2 and only slightly cooler to +37.4% Y/Y in Q3. Before that, it was an inflationary surge in Net Class 8 Tractor Orders snapping back to pre-COVID patterns. And now this month, in addition to both diesel and Class 8 patterns continuing, we get relative inventory levels flashing a still lower 1.29 in Q2 after three years of 1.36-1.40 prints. In fact, we have to go all the way back to Q1 2022 to find a lower mark. We also got both revised Q2 2026 Consumption and Q2 Industrial Production pacing flat to slightly higher, and one of our TL capacity demand indicators (ATA TL Shipments Index) breaking Y/Y inflationary for the first time since Q4 2022 – albeit barely at +0.4% Y/Y. We’ll have to wait to see how many of these hold up through subsequent revisions, but as it stands, we continue to get signals that Demand is poised to become more of a constructive force in what has up to now been a mostly supply-driven freight market rate story.
You may recall that this new cycle technically began way back in Q3 2024 with the first Y/Y inflationary close of the spot index since Q1 2022 but was unexpectedly snuffed out with April 2nd 2025’s Liberation Day and then the hostile tariff antics that have since followed. Since then, the accelerated exit of unprofitable (and in many cases non-compliant or illegally operating) carrier capacity has finally overtaken those demand headwinds, now spiking the revised Q3 2026 mark to +40.2% Y/Y vs. the prior quarter’s +33.9% Y/Y and a forecast of +45.0% Y/Y + 5.0% – to at least some degree making up for the few quarters of stalled momentum in 2025.
We noted a few issues ago that halfway through February, “spot linehaul rates had proven to remain stubbornly high for that time of year – with our revised Q1 mark currently sitting at +20.3% Y/Y vs. a forecast of +10.0% + 5.0%. While we continued to expect rates to fade at least somewhat lower in the coming weeks as some winter weather clears, we don’t believe we’re headed all the way back to November 2025 levels. Instead, in direct support of this new cycle kicking off, we believe that the market is in the process of setting a new rate floor as marginal supply continues to exit and the floor on driver wages begins to reset higher as a result”. With the Q1 closing where it did, that’s pretty much what we got. And now all of the way through August, we’ve got a revised Q3 mark of +40.2% Y/Y vs. a forecast of +45.0% Y/Y + 5.0%. So we remain right on track with regard to market guidance, after taking our forecasted cycle peaks from +45% to +50-60% on Spot and +10% to +15-20% on Contract last month.
Also as noted in recent issues, it is important to keep in mind that the spot market, based on estimates from the annual ATRI Analysis of the Operational Cost of Trucking, had been unprofitable for the last 3 years prior to last quarter, which while unprecedented over the last decade, couldn’t last forever. So what we think we’re witnessing is the inevitable reckoning, just accelerated by increased regulatory scrutiny around immigration status, non-domiciled CDL compliance, and the English language proficiency of drivers. And with a spike in diesel prices adding fuel to the proverbial fire over the last 6 months (reversing only temporarily), the pace of the reckoning will only increase. And while the magnitude of these spot market rate projections has probably appeared absurd for those using other forecasting approaches, they are entirely within the range of what we observed in past cycles. If anything, barring a material and currently unexpected downturn in the broader economy in 2026, this could prove to be conservative – as implied earlier with our commentary around spot rates potentially seeing +50-60% Y/Y and contract touching +15-20% Y/Y at peak and still operating within range of historical patterns.
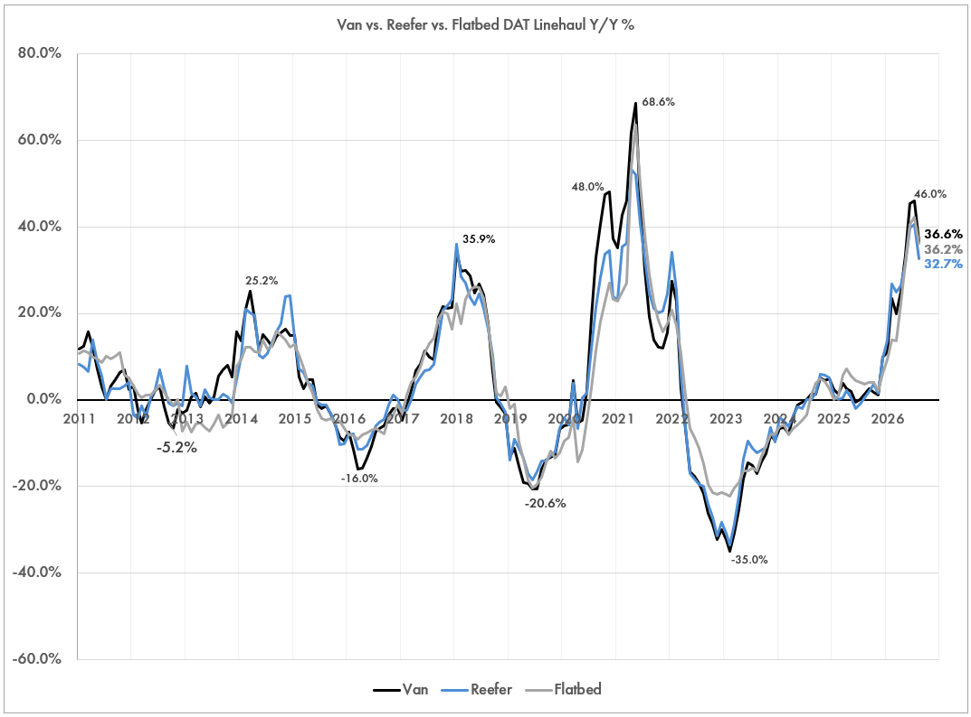
So with our forecast lines moving materially higher last month on both Spot and Contract linehaul rates, we highlighted a new chart pattern in last month’s ‘Chart of the Month’. This month we’re sticking with the same chart (to highlight the recent slowdown in rate acceleration), and taking a look inside the blended DAT Spot TL Linehaul Index itself. Recall that our spot index represents a weighted average across the three major equipment types as follows: 80% Van, 15% Reefer, 5% Flatbed. We do this to try to get to an index that represents the balance of seated tractor capacity active in the market, regardless of the type of trailer that they are hauling. As a result, we often get questions about how our index compares to what is specifically happening in the reefer market. And most recently, with the AI Data Center construction narrative fueling the assertion that the Flatbed market behaves materially differently from the Van and Reefer segments, we wanted to revisit those truckload market correlations.
In the chart below, we show the Y/Y change in DAT national linehaul rates for Van (black), Reefer (blue), and Flatbed (gray) over the last fifteen years. And while there are certainly some brief and mostly minor divergences, all three tend to move mostly in lockstep on a Y/Y basis. Is that surprising?
Recall that coming into the year, we had been highlighting a chart showing the estimated motor carrier profit per mile in the spot market through the rate cycle, illustrating just how bonkers the last few years have been. We then switched gears back to the main event – the US TL Spot and Contract linehaul rates themselves. In the spirit of “the more things change, the more they stay the same”, the last couple of issues included a rate cycle chart that went back to 2010 for a longer-term view of just how durable these year-over-year patterns in spot and contract linehaul rates have proven to be. And just how correlated the level of year-over-year US Net Class 8 Tractor Orders had been, until COVID-related and then freight recession-related distortions came along and kiboshed things. But as we’ve shown, the last few quarters suggest that this particular historical correlation is back in sync.
While we are moving on (for now) from spotlighting motor carrier profitability (or lack thereof) as the primary driver behind capacity flowing into and out of this increasingly fragmented +$900B industry, we did want to retain the main points of the narrative for any new readers this month. Feel free to skip ahead if that’s not you.
In our referenced chart, we showed the estimated motor carrier operating profit per mile through the US TL Linehaul Spot Rate Cycle going back to 2007. When the bars were in the black, that means that all-in TL spot linehaul rates (including fuel) exceeded the average estimated operating cost per mile as reported in ATRI’s annual ‘An Analysis of the Operational Costs of Trucking’ report. And when the bars were in the red, where the market had been going on 12 quarters, those operating costs (which include fuel, driver wages and benefits, lease costs, insurance, tires, tolls, etc.) exceeded the national average all-in rate per mile that the spot market is paying.
So, for enough of the supply side to sustain operations while the broader market was in the red, something we again haven’t seen in 15 years, that could only mean that were are a bunch of carriers out there with the financial resources to continue operations where every incremental mile was theoretically unprofitable (for the “average” motor carrier in the ATRI survey) – no doubt in an attempt to weather the storm and recover when the market inevitably corrects higher. And there had been a number of theories floated along the way, by Pickett Research and others, to explain how they may have been able to do so – from 3-year truck leases secured prior to lease costs surging higher with interest rates starting in early 2022 to COVID-era Small Business Administration (SBA) loan proceeds splashed around with sweetheart terms.
While some or all of those catalysts may have been a factor for many carriers along the way, it seems really hard to believe that they could have impacted the market enough to explain both the conspicuously long duration of the Y/Y deflationary leg of the last rate cycle from 2022-24 and the subsequent four to five quarters of an equally conspicuous flattening of the rate curve at < +5.0% Y/Y. But what if there was a more systemic dynamic in play that evolved right under our noses to explain this? That is exactly what we now propose as we connect the dots between the rise in non-domiciled CDL drivers and the relative market cost of that labor through the cycle.
First, consider that fuel and labor historically account for 60-70% of operating costs for the average US motor carrier – as reported by ATRI based on the carriers that respond to their survey every year. So over two-thirds of the operating expenses that compare with all-in spot market rates to form the black or red bars in the featured chart are from these two costs alone. Historically, it had been our understanding that the cost of labor doesn’t change all that much on a year-to-year basis – at least as compared to diesel prices which showed greater levels of volatility over the years and which often had a direct impact on spot market freight rates. So we tended not to focus much on labor costs and assumed that, while there were no doubt differences in those costs based on region or equipment/fleet type, the market as a whole tended to have mostly comparable labor costs on a year-to-year basis. That said, it is widely understood that owner-operators or small fleets where the owners are the ones behind the wheel, tend to have a lot more wage elasticity than larger carriers or private fleets with hired drivers. And that cost structure could allow them to operate at moderately lower freight rates than their larger competitors without going bust – for at least some period of time. And partially as a result of that, the observation had been made that a cohort of carriers clearly still existed that had found a way to profitably operate at ~$1.50/mile.
So how were they doing it? As outlined in recent months, we now believe the answer is twofold. One, just the sheer magnitude of the surge in operating authorities granted and therefore new MCs entering the market during the COVID and post-COVID boom years of 2021-24, while a number of larger fleets like Davis Express and 10 Roads have been forced to exit, suggests that the market has trended towards more fragmentation not less – so relatively more owner-ops and small fleets with more flexible cost structures than in past cycles. But we think the real story could stem from the relative rise in the cohort of non-domiciled Class A CDL drivers through the COVID cycle – accelerated by loose immigration policy and material weaknesses in the CDL examination process itself in states like CA, TX, PA, and IL.
And this dynamic is what we now believe could be the smoking gun that explains both the depth and the duration of the last freight rate recession. Left to its own devices, we believe the market would still eventually grind through its normal Darwinian process of weeding out unprofitable surplus supply over time – albeit at a much slower pace than in the past, something we have all experienced directly over the last few years. Consider that prior to 2015 when many state non-domicile CDL programs were expanded, deflationary market corrections took on average three quarters to move from their deflationary inflection point back to equilibrium. The 2016 recovery took four quarters, which was followed by a 2019 recovery that took five quarters. The 2022-24 recovery took six, before going on to stall out and hover at < +5% Y/Y for another five quarters. So while the foundational battle between supply and demand that governs overall cycle dynamics remains intact, something clearly appears to have evolved that has stretched the duration of our corrections. And we believe that “something” is materially increasing relative labor wage flexibility driven by the increasing level of fragmentation overall, but more so by the increasing proportion of non-domiciled CDL drivers out in the long-tail of owner-op and small fleet capacity.
We make no claims here around the skill, ability, or safety record of the non-domiciled and/or non-ELP-compliant CDL driver population relative to their US-domiciled counterparts. And while it’s hard to argue that non-English speaking or reading drivers don’t pose a potential safety risk to US highways, whether that has proven to be the case over the years may be unknowable. That said, none of that really matters with regard to this particular argument. The fact that ELP regulations are now being enforced during DOT inspections, the immigration status of Class 8 truck drivers is being screened at highway and facility checkpoints across the country, and non-domiciled CDL programs are being scrutinized, if not shut down altogether, will immediately begin to reverse these driver cohort trends – both by putting more drivers out of service and by making it more difficult if not impossible for new non-domiciled labor to enter the market in the first place going forward. Or in other words, the market will not be left to its own devices in the quarters ahead as spot linehaul rates seek to correct higher. An evolving regulatory landscape is going to pressure the supply-side recalibration by accelerating the exit of what we propose is a cohort of drivers and carriers that, up to this point, have been willing and able to run at materially lower labor rates than the broader market.
And that is the insight that had eluded us over the last year or two as we struggled to understand and explain why it has taken so long for the market to break Y/Y inflationary (and stay there) from its last deflationary inflection point all the way back in Q1 2023. But with market forces, in the form of federal regulatory scrutiny and now materially greater liability risk for brokers, now in place to accelerate the reversal of this trend, we expect future cycles to look a lot more like those that we observed prior to the most recent COVID and Russia-Ukraine distorted one that we are still trying to break free from. In the meantime, we now understand the extent to which the supply side has evolved over the last twenty years as a result of immigration policy and the ill-advised and ultimately untrue driver shortage narrative. So getting to more accurate and complete data on the segmentation of the estimated 3.5 million Class A CDL truck drivers that comprise the supply side of the market is going to be increasingly important when it comes to forecasting the shape of the rate cycle going forward. But we believe we are closer to understanding it now.
So with Q2 2026 closing mostly on-guidance (albeit slightly hotter at +33.9% Y/Y vs. an upper forecast range of +30%) and a revised Q3 2026 at +40.2% Y/Y vs. +45.0%, what does the current market trajectory mean with regard to expected market behavior? How are buyers and sellers likely to behave? As noted in recent issues and summarized again here for any new subscribers, with the projected spot market cycle well into inflationary territory, many enterprise procurement teams have logically looked to extend the duration of their current contracts to try and ‘keep rates locked in at the bottom’ for as long as they can get away with – which never really works over the long term yet represents a short-term temptation that is often difficult to resist. We estimate that through the duration of the most recent inflationary leg of the rate cycle from Q3 2020 to Q1 2022, TL spot linehaul rates ran at an +18.1% premium (or penalty if you’re on the buy-side) to contract rates – with the first two quarters representing the worst of it at +20-23%. This compares to an average premium/penalty of +10.4% during the last inflationary leg before that (Q2 2017 to Q4 2018), so cycle amplitudes have clearly increased, thus amplifying the relative penalty cost of the spot market altogether during this phase of the cycle.
Regardless, we should then look for many contract routing guides to continue springing leaks in the months ahead as primary tender acceptance rates continue to fall back towards 2020-21 levels – and likely to get much, much worse in an environment of rapidly dropping diesel prices and the FSCs that account for them in contract rate agreements (whenever we get back to that). That said, all is not lost if you are one of those procurement teams that run this playbook, usually under duress from a finance organization or executive leadership team looking to drive operating costs lower by any means necessary – especially as tariffs continue to bite and energy costs rise. You’ll just need to be especially agile as the freight market landscape shifts in the quarters ahead. To that end, if you haven’t done so already, we recommend that (if able) you invest in the technology and tools required to give your team the visibility and control they need to track the performance of your contract lanes and carrier partners on at least a weekly basis, and then be in a position to take decisive action if necessary – from rebidding lanes away from underperforming vendors to procuring surplus backup capacity at rates likely to be more attractive than what you’ll find later in the spot market when you need them, to leveraging more dynamic contracts that adjust more frequently based on market indices or benchmarks.
If you’re unable to position for long-term performance to begin with because global procurement best practices dictate otherwise, the next best thing is to build the operational flexibility to course correct and adapt before your competitors do as the economy and market evolve and the freight cycle marches on. In this regard, if speed is king, pre-planning is queen. The faster that shippers and carriers alike can identify meaningful market or network signals, understand their potential implications, and take action, the better they are likely to perform as we navigate these unprecedented times ahead of us.
Now on to the June macro update. After a string of mostly constructive months, last month continued the streak. Revised Q2 2026 Consumption rebounded moderately to +2.3% Y/Y, as compared with the prior quarter’s +2.1%, and continued to hold up in the face of ongoing headwinds for the American Consumer. That said, unlike the prior quarter, most of the strength was in Goods consumption, which rose 50 bps to +2.0% Y/Y. Durable Goods consumption finally arrested its descent, rising to +1.9% Y/Y vs. last quarter’s +1.1%. Nondurable Goods rose 40 bps Q/Q to post a +2.1% Y/Y. And Services rose 20 bps to +2.5% Y/Y.
Given the relatively higher freight intensity required to satisfy the demand for physical Goods, a sustained recovery in Durable and Nondurable Goods consumption would clearly be a bullish signal for future truckload capacity demand. As finished goods inventory is depleted over time, wholesale replenishment orders get triggered more frequently. If sustained, this drives factory orders higher, which then requires increased levels of industrial activity to fulfill those orders and replenish wholesale and retail inventories to satisfy future demand. And US truckload capacity is likely going to be needed to move those goods through just about every link in that chain – even more so if more of that production happens in North America as opposed to overseas. But with Goods consumption instead mostly slowing over the course of 2025, we saw no such signal, and therefore no obvious and immediate forward demand catalyst in sight for the US freight market. But with Q1 and now Q2’s revised bounce higher, there could be reason for some early optimism. And while we’ve noted constructive signals in both Industrial Production and the Inventory to Sales Ratio in recent months, both of our truckload capacity demand indicators had remained Y/Y deflationary and had yet to converge materially towards the Industrial Production line – though both have clearly made some progress recently with the ATA Index finally breaking through at a barely inflationary +0.4% Y/Y .
Now with the protagonist of our story, Consumption, continuing to make its case that US Consumers remain mostly resilient and that ongoing relative weakness in Industrial Production was unlikely to last, let’s check in with our proverbial villain – Industrial Production (IP) itself. While our dramatic yet corny ‘Consumption vs. Industrial Production: Which is telling the truth?’ storyline finally got a jolt in 2025 with IP breaking Y/Y inflationary in Q1 at +0.7% after running flat to -1.0% for nine quarters running, it went on to hit +1.7% Y/Y in Q3, slipped to +1.4% Y/Y in Q4 and +0.9% Y/Y in Q1 2026 but since closed back north at +1.5% Y/Y in Q2 before losing 30 bps to open Q3 at +1.2%. Y/Y. Recall that the entire premise behind the ‘Consumption vs. IP’ storyline was that these two indicators tended to correlate pretty closely historically. Only in rare cases, usually during an NBER recession, have we seen IP diverge materially from Consumption over the last 35 years. And with the observed recovery in IP over the last year, from -0.9% Y/Y in Q4 2024 to +1.5% Y/Y in Q2 2026 and now +1.2% Y/Y in Q3, we’ve finally just about closed one of the longest periods of divergence in chart history, which means we can finally rule in favor of Consumption in this case as it proved once again to be the more reliable indicator for the overall health of the Consumer and the US economy as a whole.
While we noted last month that, in the spirit of new beginnings and closing out stale storylines, this was one that we would put back on the shelf until the next time such a divergence begins to materialize, we’re going to string this one out for another month or two with both lines still struggling to find their footing. Given the relative weakness in our final Q1 Consumption print at +2.1% Y/Y and slight deterioration in Q3 IP at +1.2% Y/Y, we think this is worth continuing to monitor before waving the “all clear” flag on the ongoing resiliency of the US Consumer – which the War in Iran and its impact on inflation (especially at the gas pump) certainly hasn’t helped.
One of the places we’ve also continued to look for more signal is in relative inventory levels, where an accelerating Inventory-to-Sales Ratio is bearish for Industrial Production, and a decelerating ratio tends to be bullish. And just like Industrial Production from 2023-2024, this ratio ran dead flat at 1.37-1.38. But unlike Industrial Production through most of the last year, we didn’t get the same bullish signal in the form of a declining ratio value. Instead, we stayed mostly flat at 1.37-1.38. And flat is where we remained with a final Q4 2025 flashing another ho-hum 1.37. But with Q1 2026 now closing at a materially lower 1.33 and Q2 at a lower still 1.29, we’re seeing the first material break from trend in over three years. But whether it continues into Q3 or not, we’ll have to wait and see.
As we all know by now, the Inventory-to-Sales ratio historically runs inverse to Industrial Production, which makes sense as bloated inventory levels diminish the need to make more stuff to restock shelves. That means once we finally do observe a local top in the inventory-to-sales ratio, we should expect to see a local bottom in IP – and vice versa. So if a downward trajectory is sustained in the quarters ahead, it would represent an increasingly constructive signal for industrial activity, the demand for TL capacity, and the economy as a whole.
So as noted last month, if Industrial Production was really as constructive as its index suggests over recent quarters, we would have expected to see at least some downward drift in relative inventory levels in the November and December revisions. If we didn’t get any version of that, then the strength of the industrial recovery remained firmly in question until we did – or we’re able to gain more conviction elsewhere. With December coming in flat to November, which was only slightly down from October, leaving Q4 dead flat to Q3 at 1.37, we certainly didn’t get much. But with this month’s 1.29 for Q2 close now on the board, it could prove to be just the bullish future demand signal we’ve been waiting for. Again, time will tell.
With recent Consumption, Industrial Production, and relative inventory levels now all starting to show signs of potential recovery to the upside, let’s turn to our primary TL demand indicators – the Cass Shipments Index and the ATA TL Volume Index. As with relative inventory levels, we saw little to get constructive about in 2025. While perhaps the big story last year was IP finally marching higher on a Y/Y basis to once again converge with Consumption, we got the opposite with TL demand as both indicators continue to diverge to the downside from Industrial Production. After closing Q4 2025 at -7.6% Y/Y and its weakest print in over two years, the Cass Shipments Index opened Q1 2026 with an even worse -13.2% Y/Y. But with the February revision up over +10% M/M followed by more strength in March, Q1 closed at -6.2% Y/Y. And with Q2 closing higher to -3.3% Y/Y, this signaled a sustained inflection higher towards the inflationary side of the axis to eventually meet Industrial Production. Though with Q3’s preliminary mark on the board at a slightly weaker -4.6% Y/Y, the strength of that signal is going to be under some pressure. But while we’re not on the positive side of the x-axis just yet, and actually took a step backwards this month, we have made up significant ground from the Q4 2025 trough.
The ATA TL Volume Index closed Q4 2025 at its lowest print all year at -3.2% Y/Y after closing Q1 at the equilibrium line of 0.0%. But with Q1 2026 opening at a moderately stronger -2.3% Y/Y and revising still higher to close at -1.4% Y/Y, at least this one is now pointed in a more constructive direction. And with the final Q2 mark now on the board at +0.4% Y/Y and it’s first Y/Y inflationary break since Q4 2022, we get our strongest signal yet that TL capacity demand is finally aligning in support of this initial inflationary leg of Cycle 6. Though if the implied growth in Industrial Production is to be believed going forward, we will have to see a sustained bounce higher in one or both of these indicators in Q3 – but this most recent print is absolutely a strong step in that direction.
Now let’s shift our attention to the supply side and Net Class 8 US Tractor Orders, which had spent the entirety of 2025 in Y/Y deflationary territory – even with US TL Spot Linehaul Rate cycle running Y/Y inflationary (albeit only barely). But with Q1 2026 closing at +99.2% Y/Y and Q2 closing at +189.5%, both monsters and the strongest prints since Q2 2021, that has all changed. We noted here in recent months that “going forward, given the net order momentum as well as the rate momentum implied in the market, we expect our Net Class 8 US Tractor Order bars to swing positive in Q1 2026 and finally start to run increasingly inflationary – and back in convergence with the US TL Spot Linehaul rate cycle.” So now with a final Q2 on the board, that’s exactly what we are getting. But with our first glimpse at Q3 now on the board at a relatively weaker +41.9% Y/Y (but still the 3rd highest mark since Q4 2022), net order activity is showing signs of potential slowing vs. prior quarters. But maybe that should be expected given the blistering pace we saw over the first half of the year. That said, now it’s going to be all about whether YTD’s early strength holds up through future quarters to signal that historical correlation has returned before getting too excited one way or another. So far, so good though – even with this month’s relatively softer print.
While Net Class 8 Tractor Orders have bounced around over the last three or four years, the roller coaster in US retail diesel prices over the same period has been arguably even more impactful to US TL market dynamics. And with a prolonged War in Iran still keeping energy prices spiking higher for the last six months, though perhaps poised to collapse lower if a sustained peace agreement is ever reached, diesel is back in the spotlight in a big way. After bottoming out at $2.40/gal in 2020 during early COVID, prices surged 140% higher to a peak of $5.75/gal in 2022 following Russia’s invasion of Ukraine. From there, we corrected -30% lower to $3.90 by mid-2023 followed by another -10% drop to $3.52/gal by the end of 2024. Since then, the market had oscillated + 5.0% from month-to-month to reach $3.72/gal in Feb 2026 – up +5.7% vs. January and reversing a slide of -7.8% from November. Since then, with global energy prices still whipsawing with the effective opening and closing of the Strait of Hormuz and the on-again/off-again war with Iran, August diesel closed at $5.428/gal – +54.1% vs. January’s $3.523/gal but down -3.1% from May’s $5.600/gal after briefly dropping below $5/gal in June and July.
As noted in past issues and repeated here for any new readers, the last time we saw anything like 2022’s and then 2026’s spike in fuel prices (which peaked at +75.1% Y/Y in June 2022 and +60.5% Y/Y in May 2026, respectively), and now 2026’s (+60.1% Y/Y in May) was in 2008 when diesel climbed to +66.6% Y/Y that June – in the throes of The Great Recession. During that particular US TL Spot Linehaul Rate Cycle, unlike this one, diesel spiked higher several quarters ahead of spot and contract rates. As a result, we saw an unprecedented wave of motor carrier bankruptcies and exits as profitability was violently wiped out – especially for those most exposed to the spot market. The key difference in 2022 is that spot and contract rates led diesel by several quarters, which allowed the market to absorb the diesel shock without forcing carriers out of the market in material numbers at the same rate. And so far at least, it has been a much more gradual exit. As the battle between spot market rates and carrier operating costs rages on, the role that diesel prices have played has been in helping to set the ultimate market bottom where our Y/Y US TL Linehaul Spot Index line finally inflected higher as sufficient surplus capacity has been forced to exit as their operating margins evaporate. And as noted here, we believe we found that bottom with the confirmation of Q1 2023 as our deflationary inflection point. Going forward, diesel’s role remains that of a pacesetter.
So here we sit with a revised Q3 2026 print on US TL spot linehaul rates at +40.2% Y/Y and the ninth consecutive inflationary mark in a row. Consumption is still flashing mostly positive signals while Industrial Production and Relative Inventory levels show promising signs of finally breaking out of prior patterns to more constructive upside trajectories. So what’s going to move the needle on Spot TL rates one way or the other in the month ahead? While we expect mostly flat market action, relative to the last few months, we’re going with mostly the same podium from last month.
Recall that a few months ago, pole position went to the rate of supply exits from new regulatory pressures on non-compliant CDL/immigration/EPL drivers and the carriers that employ them. Since then, the Supreme Court rendered the tariffs levied under presidential IEEPA power illegal, which the Trump White House immediately followed up with a 6-month countermeasure under Section 122 of the Trade Act of 1974 taking most of the previous levies to the 15% maximum. This stood through July, at which time new Section 301 tariffs kicked in, ranging from 10% to 12.5% on roughly 60 trading partners. Up to this point, importers had a relatively brief 6-month period of tariff stability to confidently pull forward any imports previously paused during the post-Liberation Day US Trade War circus. In past issues, we suggested that if this surged imports and therefore inland freight flows like we saw in Q1 2025 (Imports +13.2% Y/Y), that would create a welcome bump in TL capacity demand – even if only temporary. Though, as we stand here in late August, while we did see a relative surge in Q2 imports at +4.2% Y/Y vs. -7.0% in the prior quarter, we didn’t see that translate into materially higher TL demand. So barring any wild developments in the months ahead, we are taking Global Trade War off the board as a potential market-moving wild card.
And of course, the Supreme Court entered the chat a couple of months ago with its unanimous ruling in Montgomery vs. Caribe Transport that the Federal Aviation Administration Act (FAAAA) does not in fact preempt state law claims against freight brokers for the negligent hiring of motor carriers. Since then, we got the first major verdict on the matter with a Texas court’s $604 million ruling against C.H. Robinson in July. So, lots of moving pieces out there, but none that warrant any changes from last month’s podium. Let’s run them down, in order of expected potential impact:
1. Diesel Prices: As noted in past issues, now that we’re well into our inflationary break higher in the Y/Y US TL Spot Linehaul rate cycle, we believe that diesel prices in the months ahead will help set the pace at which spot market rates continue to recover from here. As it stands, prices have popped +$1.90/gal or +54% higher YTD to the current August 2026 MTD mark of $5.428/mi. Prior to May, you have to go back to June 2022 to find a higher monthly average. As long as this mostly inflationary trajectory continued, we would expect to see the rate of supply exit accelerate – even with the recent move higher in spot linehaul rates since December. But as we outlined last month, we also believe that a rapid decline in diesel prices, should peace break out again in the Middle East, could set off a wave of contract re-pricing to address an increasingly negative divergence between all-in contract and spot rates.
2. Non-Compliant CDL/Immigration/EPL Driver Crackdown: We believe that the increasing scrutiny on non-EPL or CDL-compliant drivers will accelerate the exit of non-conforming drivers and fleets that currently employ them, and could represent the most meaningful supply-side catalyst in the last ten years as market labor policies evolved in response to the relentless (and wrong) driver shortage narrative. This is a big deal, and could finally explain one of the driving forces behind both the magnitude and the duration of the 2022-2025 freight recession. If the $1.50/mile marginal carrier (i.e. can still run profitably given lower relative labor costs) has left the market and isn’t coming back, should we then expect the market rate floor to rise to the breakeven point of the next cheapest (and DOT/FMCSA-compliant) carrier at +$1.90/mile? That certainly sounds like a logical outcome to all of this, but we’ll have to wait another few months or so as stricter FMCSA policies become law and new legislation makes its way through the House and the Senate before we get more clarity.
3. Increased Broker Liability without the FAAAA SCOTUS ruling and Lipe vs. Lupus Superior verdict: If a material segment of the motor carrier supply base is suddenly rendered ineligible due to a Conditional safety rating or some other combination of risk factors, as carrier vetting protocols are presumably hardened in response to increased broker (and shipper?) liability, that could accelerate spot linehaul rates higher as a result. That outcome is far from certain, however, as all market participants are forced to now adapt to materially different risk vs. reward scenarios is a rapidly rising spot market rate environment.
4. TL-Intensive US Consumer Spending: Consumer spending (as a proxy for future TL capacity demand), also somewhat of a derivative of the tariff wild card but we’ll keep separate for now, bumps back down a notch or two given the action in diesel, regulatory scrutiny, and the SCOTUS IEEPA ruling. Conditions remain tough to say the least for the average US Consumer, despite ample signal that peak Consumer Price Inflation (CPI) is well behind us after many months of slow yet uneven sequential decline. After correcting all the way from June 2022’s +9.1% Y/Y to June 2024’s +3.0% Y/Y, we had continued to fade mostly lower as prices stabilized. But with July’s print now on the board at a slightly warmer +3.4% Y/Y, based primarily on rising energy costs including gasoline, the Consumer can’t seem to catch a break. But so far at least, despite a festering affordability crisis and weakness in the labor market, US Consumers continue to consume. And so long as that remains the case, the US economy remains on a stable footing.
With the prior cycle still firmly in the rearview mirror, we can look back and reflect a bit despite the increasingly uncertain path in front of us. While the deflationary leg indeed took us far lower than those that came before (-31.8% Y/Y vs. last cycle’s -19.0%), it also took us two quarters longer than the seven-quarter deflationary leg of the last cycle (Q4 2018-Q2 2020) and the seven-quarter deflationary leg of the cycle before that (Q3 2015-Q1 2017). So, incredibly challenging market conditions for sure for most of those on the supply side, but hardly ‘unprecedented’ or ‘generational’ in nature – even considering the lower low and the longer duration. And if this cycle was more like past cycles than it was different, we should be able to anticipate typical market behavior as this Y/Y deflationary leg slowly but surely came to a close and the Y/Y inflationary leg of the new cycle began – and then recommend how best to position. So as outlined in recent issues and revised here for all of you first-time readers, we recommend some version of the following for both supply-siders and demand-siders as we start to accelerate out of the gates of this new cycle.
For motor carriers and brokers operating on the supply side of the market, this likely means keep doing what you’ve been doing over the last year and a half – at least if that means cutting costs, getting leaner, and conditioning your teams to be able to do more with less. While we absolutely see the light at the end of the tunnel with a sustained recovery in spot TL linehaul rates already in motion, the market correction is virtually guaranteed to be uneven – with different industries, geographies, and equipment types all evolving at their own pace. Also, as noted last month, while the rate of recovery can look pretty dramatic on our Y/Y cycle charts, the sequential development of the market rates each of us experiences will feel altogether different. For example, even if spot rates found a way to go on to close Y/Y inflationary in Q4 2026 at +50-60% Y/Y, that only represents a +15-20% increase from current August 2026 levels – which means we’re already three quarters of the way there.
And with the Q1 2025 TL Contract Linehaul (Cass) Index breaking Y/Y inflationary at +1.4% Y/Y for the first time since Q4 2022, Q1 2026 notching higher to +2.4%, and now a preliminary Q3 coming in at a blistering +9.3%, its trajectory from here is looking more and more certain as well. But regardless of the ultimate pace at which the market trends Y/Y inflationary over the quarters ahead, there is little downside in remaining disciplined and pursuing operational excellence in whatever it is that you do – especially now that conditions have gotten a lot more challenging with spiking diesel costs. As you prepare for the balance of 2026, the months ahead represent a welcome opportunity to refine your commercial strategy and carefully consider the shippers that you want to partner with going forward into the next cycle. So hopefully you are choosing wisely, as those who navigate the cycle most successfully over the long run tend to be the ones with the most durable long-term commercial relationships with partners that have earned their trust through both the ups and the downs.
And for shippers on the demand side of the marketplace (and brokers that operate on both sides), our guidance is similar. While the most recent Y/Y deflationary leg of the cycle has technically ended, the months ahead represent a tremendous opportunity to recalibrate your transportation strategy for the Y/Y inflationary leg that had just begun pre-trade war. The race to the bottom of the TL market that you had enjoyed through last year is over, but its lingering impact is almost certainly masking weaknesses and deficiencies that will take a toll this year if left unaddressed. So now is the time to examine your current and projected freight flows to understand where alternative modes, operating models, and capacity partners could create a comparative advantage – whether it be from cost, speed, utilization, or flexibility – in an inflationary TL market or one made all the more volatile with evolving trade conditions. With the cost of capacity increasingly on the rise, the penalty for waste only increases from here. So, focus on filling your trailers and intermodal boxes, or find a way to only pay for the space you need (the penalty cost for shipping air, or otherwise underutilized capacity, is only going up!). And work to eradicate empty miles and excessive dwell times from your networks. Remember that 2026’s, and soon 2027’s, winners will be determined by the actions taken now. Aspire to be considered a ‘Shipper of Choice’ throughout the cycle, not just when the financial pressures of an inflationary rate environment force your hand.
We continue to forecast contract linehaul rates, after breaking Y/Y inflationary in Q1 2025, to run higher through 2026 and into 2027 as primary tender acceptance rates deteriorate, routing guides spring leaks, and freight contracts are reset through a flurry of mini-bids – just like in 2017 and 2020. Though we now expect this to accelerate even further should diesel prices correct materially lower in the weeks and months ahead if we get a sustained US-Iran peace agreement, thus making all-in contract rates much less attractive as compared to the spot market. Regardless, we hope that this time around, the industry and its trading partners will have more effective tools at their disposal to make better use of the capacity that already exists in the market (across all modes) such that the supply side won’t be baited into overshooting to the same degree as in cycles past. And that the dramatic volatility of this market can begin to be tamed such that we’re not all doomed to a future defined by higher peaks and lower troughs.
But until then, the roller coaster must unfortunately continue. The market cycle itself, powered by the supply vs. demand forces that have shaped it for the last +20 years, is what will take US TL Spot Linehaul rates +15-20% higher between now and the end of the year. And so long as the trucking market continues to remain as fragmented and as largely unregulated as it has been since 1980 (this is a good thing!), with low barriers to entry and exit (and likely trending lower with the digital transformation of the spot market), the Cycle persists. And so long as the Cycle persists, the most successful market actors over the long-term, regardless of what side of the market they operate on (buy-side vs. sell-side), accept the apparent but directionally predictable chaos of the truckload market rate environment with stoic indifference. Control what you can control, then go with the flow. Whatever it is, this too shall pass. Just don’t get too complacent during this brief interlude from what has been a pretty chaotic 2026. This inflationary leg of the freight market cycle roller coaster is far from over. So buckle up and get comfortable with being uncomfortable. And watch out for those sharks.